Operator-Direct · Buying Since 2010
Turn Your Owner-Financed Note Into Cash
We purchase owner-financed and seller-financed notes, land contracts, and partial notes. Get a confidential, no-obligation evaluation and see your options.
Get My Free Note Evaluation
See How It Works
✓ Confidential ✓ No obligation ✓ Free offer in 24 hours ✓ Sell all or just part
What Is a Note
Why People Sell
Why the Discount
Sell Just Part
Notes We Buy
How It Works
FAQs
Free Evaluation
What Is a Real Estate Note?
A real estate note is a written promise to repay a loan secured by property. When the seller finances the buyer directly instead of a bank — also called owner financing or seller financing — the seller becomes the lender and holds a promissory note backed by the property. The paperwork may be called a note, a land contract, or a contract for deed depending on how it was set up, and all three can be sold for a lump sum instead of collected over years.
Owner Financing
Seller Financing
Land Contracts
Contract for Deed
How a Note Becomes Cash
Created when you owner-financed the sale.
Based on terms, payment history, and collateral.
Full purchase, partial purchase, or a hybrid.
Funds wired at closing. Borrower keeps the same loan.
Why People Sell Their Notes
There’s no single reason. Most sellers are converting a long-term income stream into capital they can use today.
➤ Stop chasing missed payments
➤ Fund a new investment
➤ Pay off debt
➤ Handle a life event
➤ Close out an inherited note
➤ Simplify an estate
➤ Get out of note servicing
Straight Answer: Why an Offer Is Less Than the Balance
Most note buyers wait until you’re on the phone to bring this up. Here it is up front.
When you sell, you’re trading years of future payments for cash in hand today. Whoever buys the note waits years to get their money back and carries the risk that the borrower stops paying along the way. That wait and that risk have a price, and that price is the discount — the same reason a prize paid out over twenty years is worth less than the same amount handed to you now.
Three things move the number more than anything else
1. What return the buyer needs
A buyer who needs an 8% return pays more than one who needs 12%. Required returns move with interest rates, so the same note is worth more in some markets than others. Outside your control.
2. The borrower’s payment history
A note where the borrower has paid every month for years sells at a smaller discount than one with missed payments behind it. More risk means a higher required return, which means a bigger discount. This one you can improve.
3. The property and the paperwork
Is the property worth more than the balance? Is the mortgage recorded and clean? Some states foreclose far faster than others, which changes how quickly a buyer could recover if things go wrong. Partly in your control.
So what can you actually do about it?
- Keep collecting, and document it. Payment history is the single biggest lever you control. A few more months of on-time payments with a clean record can move the number.
- Fix the paperwork before you sell, not during. A missing recorded mortgage or a gap in the assignment chain adds cost and risk, and that lands in the discount. Run it through JKP’s free Note Validation Tool first.
- Know that you don’t have to sell all of it. Selling only part of the note limits how much of the balance is exposed to a discount at all — see below.
Read the full breakdown, with a real example and the actual math →
You Don’t Have to Sell the Whole Note
This is the option most note-buyer websites skip. It’s called a partial, and for a lot of sellers it’s the better answer than selling everything.
How a partial works
Instead of selling the note outright, you sell a set number of the upcoming payments. JKP pays you cash today for just those payments and collects them as they come in. Once that block is collected, the note reverts to you and you go back to receiving the remaining payments for the rest of the term.
You can also sell a share of each payment rather than a block of them, or combine the two. Which structure fits depends on how much cash you need and how much of the income stream you want to keep.
Why sellers choose it
- Cash now without giving up the whole thing. Cover the expense you’re actually trying to cover, and keep the rest of the income.
- Less of the balance exposed to a discount. You’re only discounting the payments you sell, not the entire note.
- You stay the note holder. After the partial is paid off, the payments come back to you.
- It’s reversible in practice. Sell a partial now; if you later decide you want out entirely, you can sell the remainder.
What Kinds of Notes Does JKP Buy?
Performing or non-performing. First or second lien. Residential or commercial.
Single-Family Residential
Owner-occupied or rental. First or second position.
2-4 Unit Residential
Duplexes, triplexes, fourplexes secured by residential mortgages.
Commercial-Secured Notes
Mixed-use, small commercial, multi-family above 4 units. Case by case.
Performing Notes
Current borrower, on-time payment history. Best pricing.
Non-Performing Notes
Borrower in default. Active part of the JKP buy box.
Land Contracts & Contracts for Deed
Owner-financed structures on developed property.
Every Note Buyer Says “No Obligation.” Here’s the Difference.
What most note-buyer sites give you
- A generic “fast & free” pitch
- Vague or unverifiable trust badges
- No mention that a partial sale is even possible
What JKP gives you
- Dave Putz, an operator buying directly since 2010 — not a broker shopping your note around
- 1st and 2nd position notes, no upfront fees, inside a defined buy box
- The partial-sale option explained, not buried
From Note to Cash — Four Steps
Submit Your Note
Share the note, payment history, and closing statement. About 10 minutes.
Get a Written Offer
Usually within 24 hours — full purchase or partial, no upfront fees.
Title, Valuation, Due Diligence
Title search and property valuation, handled by JKP’s licensed servicers. About 2-3 weeks.
Close and Get Paid
Sign at a licensed title/escrow company. Funds wire to you. About 1 week.
Meet the Buyer
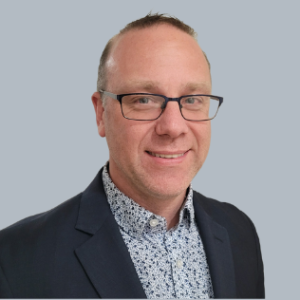
Dave Putz, Founder of JKP Holdings
Every note buyer’s website says “no obligation” and “fast.” The difference is who’s actually on the other end. Dave has been buying and selling mortgage notes since 2010 — hundreds of them over that time — and buys directly, as the operator, not as a broker shopping your note around to someone else. He also hosts the Real Estate Notes Show podcast. JKP buys both 1st and 2nd position notes, no upfront fees, inside a defined buy box. Read more about JKP Holdings.
Frequently Asked Questions
Yes — they’re two names for the same arrangement: the seller acts as the lender and the buyer makes payments directly to them instead of a bank. The resulting paper may be called a note, a land contract, or a contract for deed depending on how it was structured, but all three can be sold for cash.
No. You can sell all of it or just a portion — called a partial. You sell a set number of upcoming payments for cash today, and once those are collected the note reverts to you and you keep receiving the rest. How a partial works →
Because you’re trading years of future payments for cash today, and whoever buys the note waits years to be repaid while carrying the risk that the borrower stops paying. That wait and that risk are what the discount pays for. Three things move it most: the return the buyer needs (which follows interest rates), the borrower’s payment history, and the property and paperwork. See the full explanation with real math →
Usually within 24 hours once JKP has the note details needed to evaluate it.
No. Selling your note doesn’t require the borrower’s approval — they simply start sending payments to the new note holder after the sale closes.
No. Evaluations are free and there’s no obligation to accept.
JKP buys inside a defined 17-state buy box. Send your note details and you’ll get a straight answer on whether it fits.
Get Your Free, No-Obligation Evaluation
Share your note basics below. Dave personally reviews every submission and replies within 24 hours — no cost, no obligation.